Expanding a business beyond the UK is one of the most exciting milestones an entrepreneur can achieve. Tapping into high-demand markets across the United States, mainland Europe, Asia, and Australia unlocks massive revenue potential. However, as international sales begin rolling in, British business owners quickly run into a frustrating reality: traditional cross-border banking is slow, fragmented, and surprisingly expensive.
Managing multi-currency cash flow through conventional UK high-street banks often results in hidden foreign exchange (FX) markups, punitive receiving fees, and days of settlement lag. These operational headaches quietly erode hard-earned profit margins.
To stay competitive globally, growing companies need modern financial infrastructure built specifically for borderless commerce. Here is how modern multi-currency platforms, led by fintech innovator Airwallex, solve cross-border cash flow bottlenecks and empower UK enterprises to scale effortlessly worldwide.
The Hidden Financial Pitfalls of Traditional Cross-Border Commerce
When a UK business starts operating internationally, its daily financial operations grow exponentially more complex. Traditional banks were built for domestic commerce, which creates distinct friction points across three critical business activities:
1. Receiving International Client & Marketplace Payments
Selling products on global marketplaces like Amazon US or Shopify Europe, or billing overseas corporate clients in US Dollars (USD) or Euros (EUR), typically requires local banking details.
Without them, payments must travel over the legacy SWIFT network. Along the way:
- Intermediary correspondent banks deduct hidden handling fees (often £15 to £30 per wire).
- Traditional UK banks automatically force the incoming payment to convert into British Pounds (GBP) upon arrival, applying inflated exchange rates that sit 2% to 4% above the real interbank mid-market rate.
2. Paying Overseas Suppliers and Remote Contractors
Most UK e-commerce brands source inventory from overseas manufacturers, while digital agencies frequently employ software developers, designers, and marketers across different continents.
Paying these global partners from a standard GBP business account creates a double conversion trap:
- You convert client USD into GBP when you get paid.
- You then convert that same GBP back into USD, EUR, or RMB to pay your manufacturer or vendor.
- Every single back-and-forth conversion costs your business a percentage of the total transaction.
3. Juggling Fragmented Multi-Currency Balances
To avoid constant forced conversions, some companies attempt to open foreign currency accounts with traditional high-street banks. This process is notoriously cumbersome, requiring weeks of branch visits, voluminous paperwork, and hefty monthly maintenance fees per currency line.
Worse still, these accounts rarely communicate smoothly with your UK accounting software, creating reconciliation nightmares for finance teams at month-end.
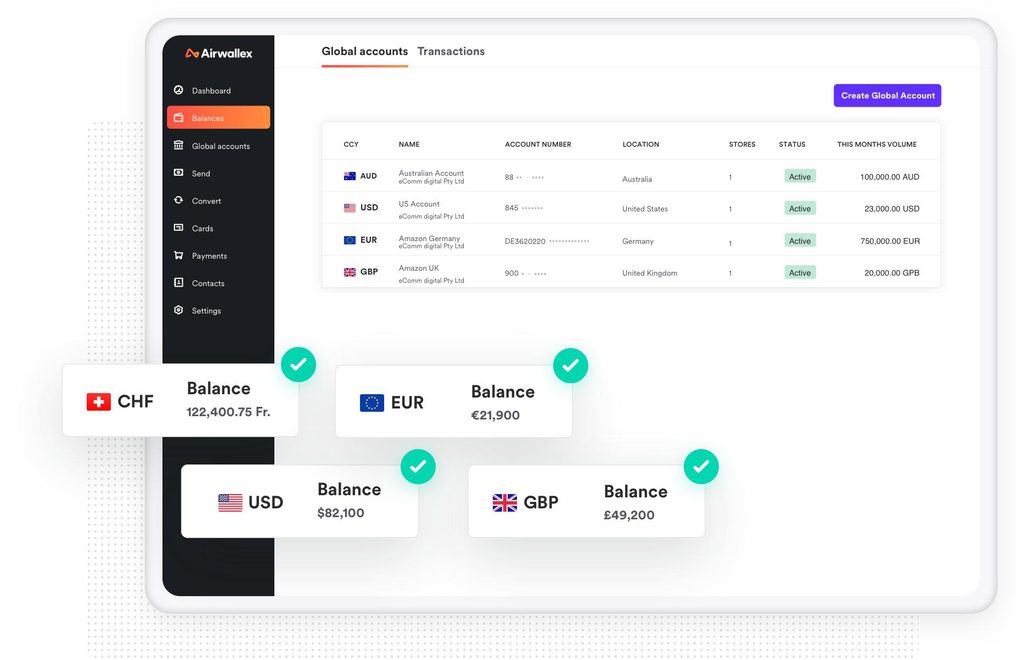
How Airwallex Transforms Cross-Border Treasury Workflows
Airwallex replaces this legacy friction with a unified, software-driven financial operating system. Instead of maintaining disconnected bank accounts in every country where you do business, Airwallex provides an end-to-end multi-currency setup from a single centralized dashboard.
Open Local Currency Accounts Without Foreign Entities
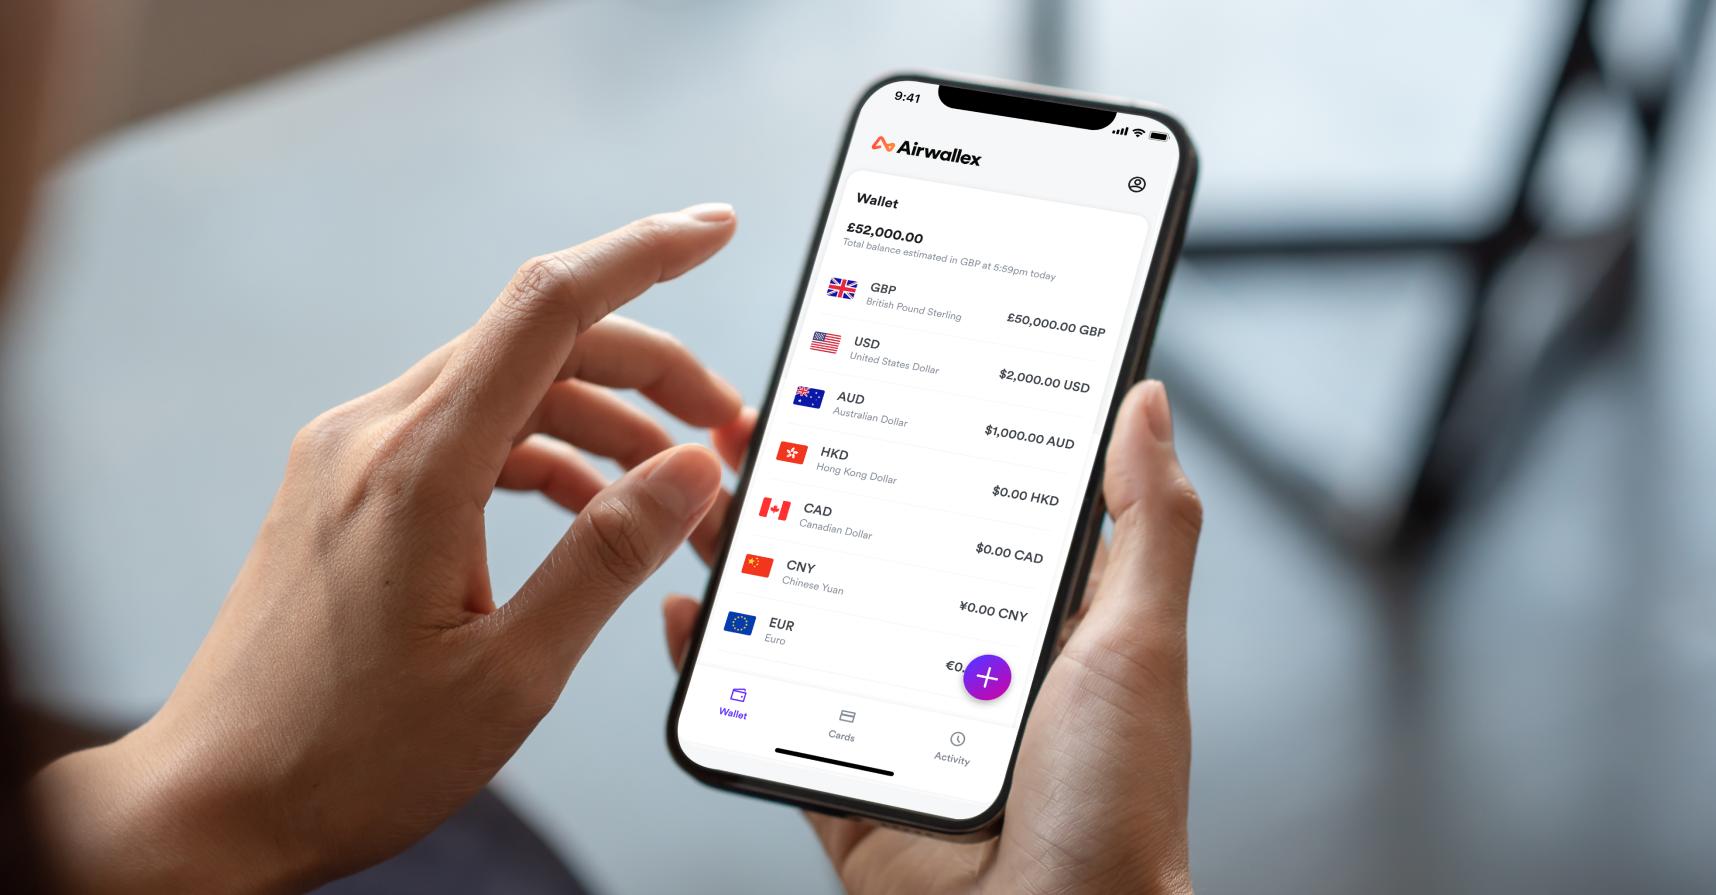
Through Airwallex, a UK-registered company can instantly generate local collection accounts in over 60 countries and regions—including domestic account details for USD, EUR, GBP, AUD, CAD, HKD, SGD, and JPY.
- How it helps: When selling to an American client, you simply provide them with a US routing number and account number. The client pays via domestic ACH wire just as if you were an American firm.
- The benefit: Zero intermediary SWIFT fees, same-day settlement, and zero forced currency conversions.
Hold, Manage, and Like-for-Like Settlement
The real power of a modern multi-currency account lies in like-for-like settlement.
When an American customer pays you $10,000 USD, that money settles directly into your Airwallex USD balance as native US Dollars. You are not forced to convert it into Sterling. You can hold that USD balance indefinitely and use it directly to pay an American software vendor, settle a Facebook Ads invoice, or wire funds to an Asian supplier without losing a single penny to currency conversions.
Institutional FX Rates with Zero Hidden Fees
When you do need to convert funds, such as bringing international revenue home to cover UK payroll or domestic tax obligations, Airwallex provides access to real-time interbank foreign exchange rates with transparent, minimal markups (often as low as 0.4% to 0.6% above the interbank rate, compared to 3% to 5% at traditional commercial banks).
Multi-Currency Borderless Corporate Cards
Airwallex allows businesses to issue instant virtual and physical corporate employee cards powered by Visa.
These cards automatically draw funds directly from the matching currency wallet balance. If a marketing manager buys Google Ads in USD, the card pulls directly from your USD account balance with 0% international transaction fees, saving thousands on recurring corporate SaaS and marketing expenses.
Seamless Accounting Integration with Xero and QuickBooks
Managing multiple currencies can easily break bookkeeping workflows. Airwallex features native, multi-currency bank feeds that integrate directly into platforms like Xero, QuickBooks, and NetSuite. Transactions, foreign exchange gains/losses, and merchant fee deductions synchronize automatically, allowing your finance team to reconcile global accounts in minutes rather than days.
Direct Cost Comparison: Traditional UK Bank vs. Airwallex
| Operational Workflow | Traditional UK High-Street Bank | Airwallex Multi-Currency Setup |
| Account Opening Time | 2 to 6 weeks per international account | Instant digital setup for 60+ countries |
| FX Conversion Markup | 2.5% to 4.5% above interbank rate | Transparent 0.4% to 0.6% margin |
| Incoming SWIFT Fees | £15 to £30 deducted per transfer | £0 via local clearing networks (ACH, SEPA) |
| Like-for-Like Settlement | Rarely supported (auto-converts to GBP) | Full native support across 20+ held currencies |
| Corporate Card FX Fees | 2.75% to 3% per overseas transaction | 0% international transaction fees on held currencies |
| Accounting Sync | Manual CSV imports & manual reconciliation | Real-time automated multi-currency bank feeds |
Practical Blueprint: Scaling a UK Brand Globally
To visualize how this works in practice, consider a fast-growing UK e-commerce apparel brand expanding into the United States and Europe:
- Local Checkout Setup: The brand connects its Airwallex USD and EUR local collection accounts to Shopify Payments and Stripe.
- Receiving Revenue: US shoppers pay in USD via card, and European shoppers pay in EUR via local bank rails (SEPA). Funds land natively in the brand’s separate USD and EUR Airwallex wallets.
- Automating Operational Expenses: The company uses its USD balance to pay for Shopify apps and Meta advertising campaigns using virtual Airwallex corporate cards.
- Paying Supply Chains: The company pays its packaging manufacturer in Europe directly from its EUR wallet via local SEPA rails, avoiding SWIFT wire costs.
- Repatriating Profits: At the end of the quarter, the remaining profit margins are converted into GBP at interbank exchange rates and swept into their primary UK operating account.
By removing unnecessary conversions at every step, this simple workflow optimization routinely adds 3% to 5% straight back to a company’s bottom line.
FAQs
Is Airwallex a bank, and are my business funds safe?
Airwallex is a licensed Electronic Money Institution (EMI) authorized and regulated in the UK by the Financial Conduct Authority (FCA). Rather than using customer deposits for lending like traditional commercial banks, Airwallex safeguards 100% of client funds in ring-fenced accounts held with top-tier systemic global banking institutions.
Can I connect Airwallex directly to Amazon, eBay, and PayPal?
Yes. Airwallex is fully integrated with global marketplace ecosystems. You can link your local USD, EUR, AUD, or CAD collection details directly to Amazon Seller Central, PayPal, Stripe, eBay, and Etsy to receive seller payouts in native currencies without paying high marketplace conversion penalties.
Do I need registered business entities in the US or Europe to open local accounts?
No. That is one of the primary advantages for UK businesses. You can open local collection account details in the US, Europe, Australia, and dozens of other markets using your existing UK company registration documents without incorporating separate foreign entities.
What is the difference between SWIFT and local clearing networks?
SWIFT is an international messaging network that routes money across multiple intermediary banks, resulting in slower transfers (2 to 5 business days) and high processing fees. Local clearing networks (like Faster Payments in the UK, ACH in the US, and SEPA in Europe) process payments domestically, delivering near-instant settlements at a fraction of the cost.
Can I set custom spend limits on employee corporate cards?
Yes. Administrators can issue unlimited virtual corporate cards instantly and apply granular controls, such as daily or monthly spend caps, merchant category restrictions, and single-use budget parameters, directly from the management portal.